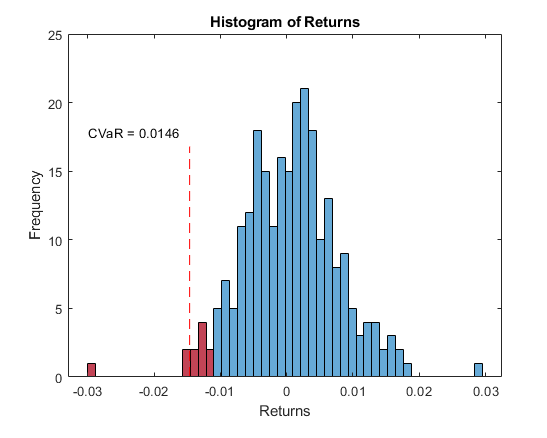
CVaR Portfolio Optimization
Conditional Value at Risk (CVaR) portfolio optimization with the PortfolioCVaR object

Sie verfolgen jetzt diese Einreichung
- Aktualisierungen können Sie in Ihrem Feed verfolgter Inhalte sehen.
- Je nach Ihren Kommunikationseinstellungen können Sie auch E-Mails erhalten.
Zitieren als
MathWorks Quant Team (2026). CVaR Portfolio Optimization (https://de.mathworks.com/matlabcentral/fileexchange/38288-cvar-portfolio-optimization), MATLAB Central File Exchange. Abgerufen .
Kategorien
Mehr zu Portfolio Optimization for Asset Allocation finden Sie in Help Center und MATLAB Answers
Allgemeine Informationen
- Version (273 KB)
Kompatibilität der MATLAB-Version
- Kompatibel mit R2018a und späteren Versionen
Plattform-Kompatibilität
- Windows
- macOS
- Linux
| Version | Veröffentlicht | Versionshinweise | Action |
|---|---|---|---|
| 2.0.0 | Major update for the example using newer capabilities of MATLAB and Toolboxes |
||
| 1.3.0 | Updated license |
||
| 1.3.0-0 | Minor code cleanup, fixed some typos in comments. |
||
| 1.0.0 |

