a = arcov(x,p)
returns the normalized autoregressive (AR) parameters corresponding to a model of order
p for the input array x, where
x is assumed to be the output of an AR system driven by white noise.
This method minimizes the forward prediction error in the least-squares sense.
Use a vector of polynomial coefficients to generate an AR(4) process by filtering 1024 samples of white noise. Use the covariance method to estimate the coefficients.
A = [1 -2.7607 3.8106 -2.6535 0.9238];
y = filter(1,A,0.2*randn(1024,1));
arcoeffs = arcov(y,4)
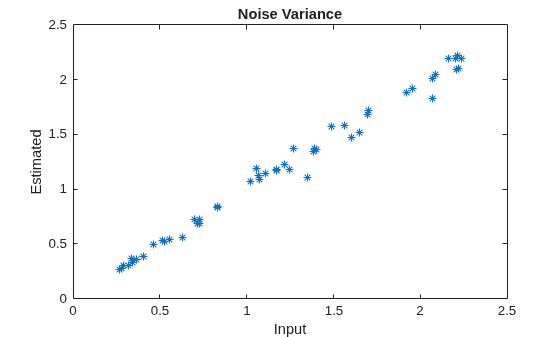
Generate 50 realizations of the process, changing each time the variance of the input noise. Compare the covariance-estimated variances to the actual values.
nrealiz = 50;
noisestdz = rand(1,nrealiz) + 0.5;
randnoise = randn(1024,nrealiz);
noisevar = zeros(1,nrealiz);
for k = 1:nrealiz
y = filter(1,A,noisestdz(k) * randnoise(:,k));
[arcoeffs,noisevar(k)] = arcov(y,4);
end
plot(noisestdz.^2,noisevar,"*")
title("Noise Variance")
xlabel("Input")
ylabel("Estimated")
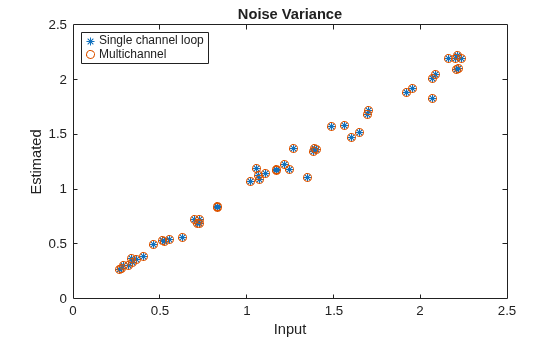
Repeat the procedure using the function's multichannel syntax.
Y = filter(1,A,noisestdz.*randnoise);
[coeffs,variances] = arcov(Y,4);
hold on
plot(noisestdz.^2,variances,"o")
hold off
legend("Single channel loop","Multichannel",Location="best")
Normalized autoregressive parameters, returned as a vector or matrix. If
x is a matrix, then each row of a
corresponds to a column of x. a has p + 1 columns and contains the AR system parameters, A(z), in descending powers of z.
White noise input variance, returned as a scalar or row vector. If x is a
matrix, then each element of e corresponds to a column of
x.
In an AR model of order p, the current output is a
linear combination of the past p outputs plus a white noise input. The
weights on the p past outputs minimize the mean squared prediction error
of the autoregression.
Let y(n) be a wide-sense stationary random process obtained by filtering white
noise of variance e with the system function A(z). If Py(ejω) is the power spectral density of y(n), then
Because the covariance method characterizes the input data using an all-pole model, the
correct choice of the model order, p, is important.
You clicked a link that corresponds to this MATLAB command:
Run the command by entering it in the MATLAB Command Window.
Web browsers do not support MATLAB commands.
Website auswählen
Wählen Sie eine Website aus, um übersetzte Inhalte (sofern verfügbar) sowie lokale Veranstaltungen und Angebote anzuzeigen. Auf der Grundlage Ihres Standorts empfehlen wir Ihnen die folgende Auswahl: .
Sie können auch eine Website aus der folgenden Liste auswählen:
So erhalten Sie die bestmögliche Leistung auf der Website
Wählen Sie für die bestmögliche Website-Leistung die Website für China (auf Chinesisch oder Englisch). Andere landesspezifische Websites von MathWorks sind für Besuche von Ihrem Standort aus nicht optimiert.