Asset Returns and Moments of Asset Returns Using Portfolio Object
R2026bSince mean-variance portfolio optimization problems require estimates for the mean and
covariance of asset returns, the Portfolio object has several ways to
set and get the properties AssetMean (for the mean) and
AssetCovar (for the covariance). In addition, the return for a
riskless asset is kept in the property RiskFreeRate so that all
assets in AssetMean and AssetCovar are risky
assets. For information on the workflow when using Portfolio objects,
see Portfolio Object Workflow.
Assignment Using the Portfolio Function
Suppose that you have a mean and covariance of asset returns in variables
m and C. The properties for the moments of
asset returns are set using the Portfolio
object:
m = [ 0.05; 0.1; 0.12; 0.18 ];
C = [ 0.0064 0.00408 0.00192 0;
    0.00408 0.0289 0.0204 0.0119;
    0.00192 0.0204 0.0576 0.0336;
    0 0.0119 0.0336 0.1225 ];
m = m/12;
C = C/12;
p = Portfolio('AssetMean', m, 'AssetCovar', C);
disp(p.NumAssets)
disp(p.AssetMean)
disp(p.AssetCovar)
4
0.0042
0.0083
0.0100
0.0150
0.0005 0.0003 0.0002 0
0.0003 0.0024 0.0017 0.0010
0.0002 0.0017 0.0048 0.0028
0 0.0010 0.0028 0.0102NumAssets from the moments. The Portfolio object enables separate
initialization of the moments, for
example:m = [ 0.05; 0.1; 0.12; 0.18 ];
C = [ 0.0064 0.00408 0.00192 0;
0.00408 0.0289 0.0204 0.0119;
0.00192 0.0204 0.0576 0.0336;
0 0.0119 0.0336 0.1225 ];
m = m/12;
C = C/12;
p = Portfolio;
p = Portfolio(p, 'AssetMean', m);
p = Portfolio(p, 'AssetCovar', C);
[assetmean, assetcovar] = p.getAssetMomentsassetmean =
0.0042
0.0083
0.0100
0.0150
assetcovar =
0.0005 0.0003 0.0002 0
0.0003 0.0024 0.0017 0.0010
0.0002 0.0017 0.0048 0.0028
0 0.0010 0.0028 0.0102getAssetMoments function lets you
get the values for AssetMean and AssetCovar
properties at the same time.Assignment Using the setAssetMoments Function
You can also set asset moment properties using the setAssetMoments function. For
example, given the mean and covariance of asset returns in the variables
m and C, the asset moment properties can
be
set:
m = [ 0.05; 0.1; 0.12; 0.18 ];
C = [ 0.0064 0.00408 0.00192 0;
    0.00408 0.0289 0.0204 0.0119;
    0.00192 0.0204 0.0576 0.0336;
    0 0.0119 0.0336 0.1225 ];
m = m/12;
C = C/12;

p = Portfolio;
p = setAssetMoments(p, m, C);
[assetmean, assetcovar] = getAssetMoments(p)
assetmean =
0.0042
0.0083
0.0100
0.0150
assetcovar =
0.0005 0.0003 0.0002 0
0.0003 0.0024 0.0017 0.0010
0.0002 0.0017 0.0048 0.0028
0 0.0010 0.0028 0.0102Scalar Expansion of Arguments
Both the Portfolio object and the setAssetMoments function perform
scalar expansion on arguments for the moments of asset returns. When using the
Portfolio object, the number of
assets must be already specified in the variable NumAssets. If
NumAssets has not already been set, a scalar argument is
interpreted as a scalar with NumAssets set to
1. setAssetMoments provides an
additional optional argument to specify the number of assets so that scalar
expansion works with the correct number of assets. In addition, if either a scalar
or vector is input for the covariance of asset returns, a diagonal matrix is formed
such that a scalar expands along the diagonal and a vector becomes the diagonal.
This example demonstrates scalar expansion for four jointly independent assets with
a common mean 0.1 and common variance
0.03:
p = Portfolio;
p = setAssetMoments(p, 0.1, 0.03, 4);
[assetmean, assetcovar] = getAssetMoments(p)
assetmean =

    0.1000
    0.1000
    0.1000
    0.1000

assetcovar =

    0.0300         0         0         0
         0    0.0300         0         0
         0         0    0.0300         0
0 0 0 0.0300NumAssets argument. This example illustrates a
constant-diagonal covariance matrix and a mean of asset returns for four
assets:p = Portfolio; p = setAssetMoments(p, [ 0.05; 0.06; 0.04; 0.03 ], 0.03); [assetmean, assetcovar] = getAssetMoments(p)
assetmean =

    0.0500
    0.0600
    0.0400
    0.0300

assetcovar =

    0.0300         0         0         0
         0    0.0300         0         0
         0         0    0.0300         0
0 0 0 0.0300Portfolio object if
NumAssets is known, or is deduced from the inputs.Estimate Mean and Covariance of Asset Returns from Data for a Portfolio Object
This example shows how to use the estimateAssetMoments function to estimate the mean and covariance of asset returns from data for a Portfolio object.
Generate random samples of 120 observations of asset returns for four assets from known mean and covariance values using the portsim function. Also create a corresponding price series from the returns.
m = [0.05 0.1 0.12 0.18];
C = [0.0064 0.00408 0.00192 0;
     0.00408 0.0289 0.0204 0.0119;
     0.00192 0.0204 0.0576 0.0336;
     0 0.0119 0.0336 0.1225];
m = m/12;
C = C/12;
X = portsim(m,C,120);
Y = ret2tick(X);
Create a Portfolio object and estimate asset moments from the return data in X using the estimateAssetMoments function. Compare the estimated moments with directly assigned moments.
p = Portfolio(AssetMean=m,AssetCovar=C);
q = Portfolio;
q = estimateAssetMoments(q,X);

[pMean,pCovar] = getAssetMoments(p)
pMean = 4×1

    0.0042
    0.0083
    0.0100
    0.0150
pCovar = 4×4

    0.0005    0.0003    0.0002         0
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
         0    0.0010    0.0028    0.0102
[qMean,qCovar] = getAssetMoments(q)
qMean = 4×1

    0.0042
    0.0083
    0.0100
    0.0150
qCovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
    0.0000    0.0010    0.0028    0.0102
Both approaches yield the same moments because the portsim function creates simulated data with estimated mean and covariance identical to the input moments.
If you have asset prices instead of returns, specify the DataFormat name-value argument set as "Prices" to indicate that the input data contains prices.
r = Portfolio;
r = estimateAssetMoments(r,Y,DataFormat="Prices");

[rMean,rCovar] = getAssetMoments(r)
rMean = 4×1
0.0042
0.0083
0.0100
0.0150
rCovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
    0.0000    0.0010    0.0028    0.0102
The estimated moments from prices match those estimated from returns.
Estimating Asset Moments with Missing Data
This example shows how to work with missing data indicated by NaN values in your return or price data. Although Multivariate Normal Regression goes into detail about regression with missing data, the estimateAssetMoments function has a name-value pair argument name 'MissingData' that indicates with a Boolean value whether to use the missing data capabilities of Financial Toolbox™ software. The default value for 'MissingData' is false which removes all samples with NaN values. If, however, 'MissingData' is set to true, estimateAssetMoments uses the ECM algorithm to estimate asset moments. The following code illustrates how this works on price data with missing values:
m = [ 0.05; 0.1; 0.12; 0.18 ];
C = [ 0.0064 0.00408 0.00192 0;
      0.00408 0.0289 0.0204 0.0119;
      0.00192 0.0204 0.0576 0.0336;
      0 0.0119 0.0336 0.1225 ];
m = m/12;
C = C/12;

X = portsim(m', C, 120);
Y = ret2tick(X);
Y(1:20,1) = NaN;
Y(1:12,4) = NaN;

p = Portfolio('mean',m,'covar',C);

q = Portfolio;
q = estimateAssetMoments(q, Y, 'dataformat', 'prices');

r = Portfolio;
r = estimateAssetMoments(r, Y, 'dataformat', 'prices', 'missingdata', true);

[passetmean, passetcovar] = getAssetMoments(p)
passetmean = 4×1
0.0042
0.0083
0.0100
0.0150
passetcovar = 4×4

    0.0005    0.0003    0.0002         0
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
         0    0.0010    0.0028    0.0102
[qassetmean, qassetcovar] = getAssetMoments(q)
qassetmean = 4×1

    0.0039
    0.0128
    0.0153
    0.0238
qassetcovar = 4×4

    0.0006    0.0004    0.0001    0.0001
    0.0004    0.0023    0.0015    0.0005
    0.0001    0.0015    0.0043    0.0024
    0.0001    0.0005    0.0024    0.0084
[rassetmean, rassetcovar] = getAssetMoments(r)
rassetmean = 4×1

    0.0033
    0.0083
    0.0100
    0.0176
rassetcovar = 4×4

    0.0006    0.0004    0.0001    0.0001
    0.0004    0.0024    0.0017    0.0007
    0.0001    0.0017    0.0048    0.0025
    0.0001    0.0007    0.0025    0.0083
The Portfolio object p contains raw moments, the Portfolio object q contains estimated moments in which NaN values are discarded, and the Portfolio object r contains raw moments that accommodate missing values. Each time you run this code, you will get different estimates for the moments in q and r, and these will also differ from the moments in p.
Estimating Asset Moments from Time Series Data
This example shows how the estimateAssetMoments function also accepts asset returns or prices stored in a table or timetable. estimateAssetMoments implicitly works with matrices of data or data in a table or timetable object using the same rules for whether the data are returns or prices.
To illustrate the use of a table and timetable, use array2table and array2timetable to create a table and a timetable that contain asset returns generated with portsim (see Estimate Mean and Covariance of Asset Returns from Data for a Portfolio Object). Two portfolio objects are then created with the AssetReturns based on a table and a timetable object.
m = [ 0.05; 0.1; 0.12; 0.18 ];
C = [ 0.0064 0.00408 0.00192 0;
      0.00408 0.0289 0.0204 0.0119;
      0.00192 0.0204 0.0576 0.0336;
      0 0.0119 0.0336 0.1225 ];
m = m/12;
C = C/12;

assetRetnScenarios = portsim(m', C, 120);
dates = datetime(datenum(2001,1:120,31), 'ConvertFrom', 'datenum');
assetsName = {'Bonds', 'LargeCap', 'SmallCap', 'Emerging'};
assetRetnTimeTable = array2timetable(assetRetnScenarios,'RowTimes',dates, 'VariableNames', assetsName);
assetRetnTable = array2table(assetRetnScenarios, 'VariableNames', assetsName);


% Create two Portfolio objects:
% p with predefined mean and covar and q with asset return scenarios to estimate mean and covar.
p = Portfolio('mean', m, 'covar', C);
q = Portfolio;

% Estimate asset moments using a timetable
q = estimateAssetMoments(q, assetRetnTimeTable);
[passetmean, passetcovar] = getAssetMoments(p)
passetmean = 4×1
0.0042
0.0083
0.0100
0.0150
passetcovar = 4×4

    0.0005    0.0003    0.0002         0
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
         0    0.0010    0.0028    0.0102
[qassetmean, qassetcovar] = getAssetMoments(q)
qassetmean = 4×1

    0.0042
    0.0083
    0.0100
    0.0150
qassetcovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
    0.0000    0.0010    0.0028    0.0102
% Estimate asset moments using a table
q = estimateAssetMoments(q, assetRetnTable);
[passetmean, passetcovar] = getAssetMoments(p)
passetmean = 4×1
0.0042
0.0083
0.0100
0.0150
passetcovar = 4×4

    0.0005    0.0003    0.0002         0
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
         0    0.0010    0.0028    0.0102
[qassetmean, qassetcovar] = getAssetMoments(q)
qassetmean = 4×1

    0.0042
    0.0083
    0.0100
    0.0150
qassetcovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
    0.0000    0.0010    0.0028    0.0102
As you can see, the moments match between th two portfolios. In addition, estimateAssetMoments also extracts asset names or identifiers from a table or timetable when the argument name 'GetAssetList' is set to true (its default value is false). If the 'GetAssetList' value is true, the identifiers are used to set the AssetList property of the Portfolio object. To show this, the formation of the Portfolio object q is repeated from the previous code with the 'GetAssetList' flag set to true and this extracts the column labels from a table or timetable object.
q = estimateAssetMoments(q,assetRetnTable,'GetAssetList',true);
disp(q.AssetList)
{'Bonds'} {'LargeCap'} {'SmallCap'} {'Emerging'}
Note if you set the 'GetAssetList' flag set to true and your input data is in a matrix, estimateAssetMoments uses the default labeling scheme from setAssetList described in Setting Up a List of Asset Identifiers.
Estimate Weighted Asset Moments Using Entropy Pooling Probabilities
This example shows how to use the Probabilities name-value argument of the estimateAssetMoments function to estimate asset moments weighted by entropy pooling posterior probabilities. Entropy pooling produces posterior probabilities that incorporate your market views into an empirical distribution. You can pass these probabilities directly to the estimateAssetMoments function to compute the weighted mean and covariance for mean-variance portfolio optimization.
Load historical asset return data. For this example, simulate asset returns for a portfolio of four assets.
rng("default")
m = [0.05 0.1 0.12 0.18];
C = [0.0064 0.00408 0.00192 0;
     0.00408 0.0289 0.0204 0.0119;
     0.00192 0.0204 0.0576 0.0336;
     0 0.0119 0.0336 0.1225];
m = m/12;
C = C/12;
AssetReturns = portsim(m,C,240);
Create an entropyViews object from the asset returns and specify a view that the mean return of the first asset is greater than its historical average.
obj = entropyViews(AssetReturns);
obj = setMeanViews(obj,"Var1",">",0.006);
Compute posterior probabilities that reflect the specified views while minimizing relative entropy.
p = posteriorProbabilities(obj);
Pass the posterior probabilities to the estimateAssetMoments function using the Probabilities name-value argument. The function computes the weighted mean and population covariance.
port = Portfolio;
port = estimateAssetMoments(port,AssetReturns,Probabilities=p);
[weightedMean,weightedCovar] = getAssetMoments(port)
weightedMean = 4×1

    0.0060
    0.0095
    0.0106
    0.0150
weightedCovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0009
    0.0002    0.0017    0.0047    0.0027
    0.0000    0.0009    0.0027    0.0100
Compare the probability-weighted moments against the standard equally weighted estimation to see the impact of the entropy pooling views.
portNeutral = Portfolio;
portNeutral = estimateAssetMoments(portNeutral,AssetReturns);
[equalMean,equalCovar] = getAssetMoments(portNeutral)
equalMean = 4×1

    0.0042
    0.0083
    0.0100
    0.0150
equalCovar = 4×4

    0.0005    0.0003    0.0002    0.0000
    0.0003    0.0024    0.0017    0.0010
    0.0002    0.0017    0.0048    0.0028
    0.0000    0.0010    0.0028    0.0102
The mean of the first asset in the portfolio that reflects the view is higher than the mean of the first asset in the neutral portfolio, reflecting the view that its expected return is at least 0.006.
Set default portfolio constraints and compute the efficient frontier for both the weighted and neutral portfolios.
port = setDefaultConstraints(port);
portNeutral = setDefaultConstraints(portNeutral);

pgt = estimateFrontier(port,20);
pngt = estimateFrontier(portNeutral,20);
Plot the efficient frontiers.
ax = axes;
hold(ax,"on")
[~,~,h1] = plotFrontier(port,pgt,Parent=ax);
[~,~,h2] = plotFrontier(portNeutral,pngt,Parent=ax);
h2.Color = "r";
h2.LineStyle = ":";
xlabel("Portfolio Risk (Standard Deviation)")
ylabel("Portfolio Return")
legend("Entropy Pooling Weighted","Neutral",Location="southeast")
title("Efficient Frontiers: Entropy Pooling Weighted vs. Neutral")
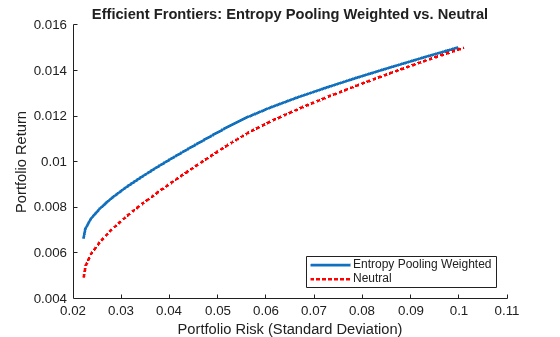
The efficient frontier shifts when you incorporate entropy pooling views, reflecting the updated distribution of asset returns.
See Also
Portfolio | entropyViews | estimateAssetMoments | getAssetMoments | setAssetMoments | setCosts
Topics
- Creating the Portfolio Object
- Working with Portfolio Constraints Using Defaults
- Validate the Portfolio Problem for Portfolio Object
- Estimate Efficient Portfolios for Entire Efficient Frontier for Portfolio Object
- Estimate Efficient Frontiers for Portfolio Object
- Asset Allocation Case Study
- Portfolio Optimization Examples Using Financial Toolbox
- Portfolio Optimization with Semicontinuous and Cardinality Constraints
- Black-Litterman Portfolio Optimization Using Financial Toolbox
- Portfolio Optimization Using Factor Models
- Portfolio Optimization Using Social Performance Measure
- Diversify Portfolios Using Custom Objective
- Portfolio Object
- Portfolio Optimization Theory
- Portfolio Object Workflow

