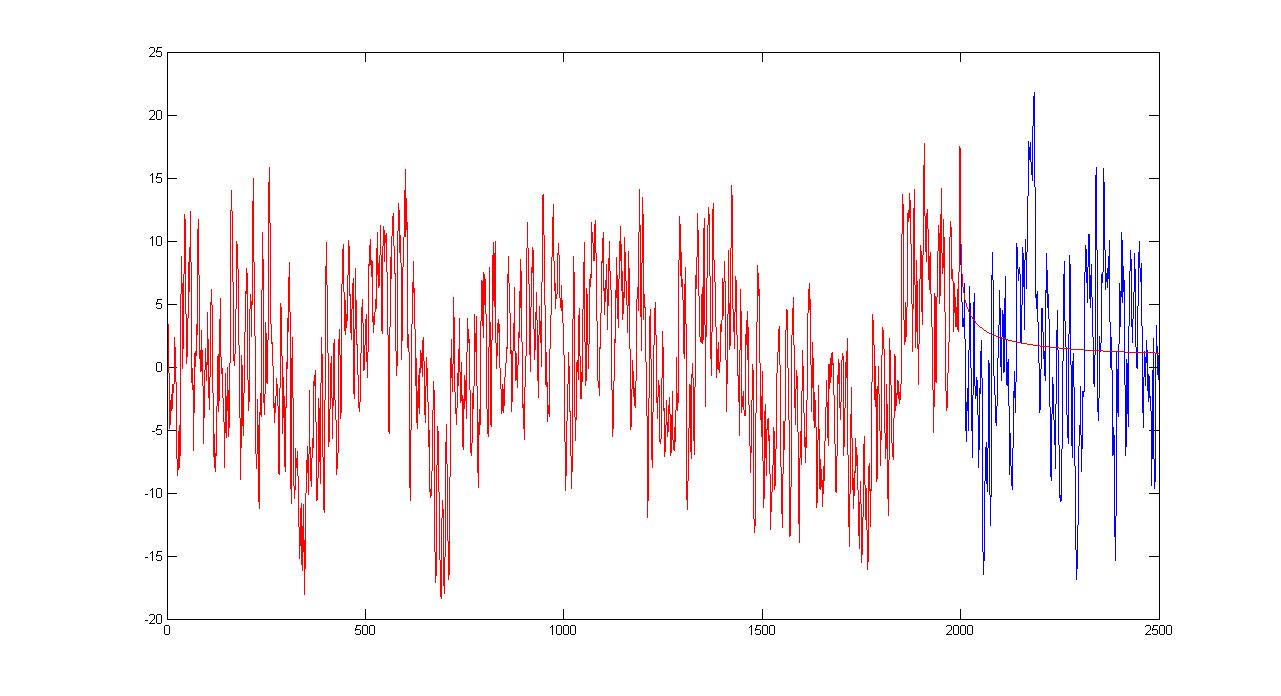
ARFIMA(p,d,q) estimator
Maximum likelihood estimators of stationary univariate ARFIMA(p,d,q) processes.

Sie verfolgen jetzt diese Einreichung
- Aktualisierungen können Sie in Ihrem Feed verfolgter Inhalte sehen.
- Je nach Ihren Kommunikationseinstellungen können Sie auch E-Mails erhalten.
Zitieren als
György Inzelt (2026). ARFIMA(p,d,q) estimator (https://de.mathworks.com/matlabcentral/fileexchange/30238-arfima-p-d-q-estimator), MATLAB Central File Exchange. Abgerufen .
Quellenangaben
Inspiriert von: MexWizard, howto: mex + MS Visual C/C++ Express Edition 2005, C++ MEX symbolic debugging, ARFIMA simulations
Allgemeine Informationen
- Version (12,3 KB)
Kompatibilität der MATLAB-Version
- Kompatibel mit allen Versionen
Plattform-Kompatibilität
- Windows
- macOS
- Linux
| Version | Veröffentlicht | Versionshinweise | Action |
|---|---|---|---|
| 1.1.0 | Added the exact maximum likelihood estimator, a covariance computing algorithm and a forecasting function. Also, the code is more clean and easier to use. |
||
| 1.0.0 |

